Why Structured Reporting Exists
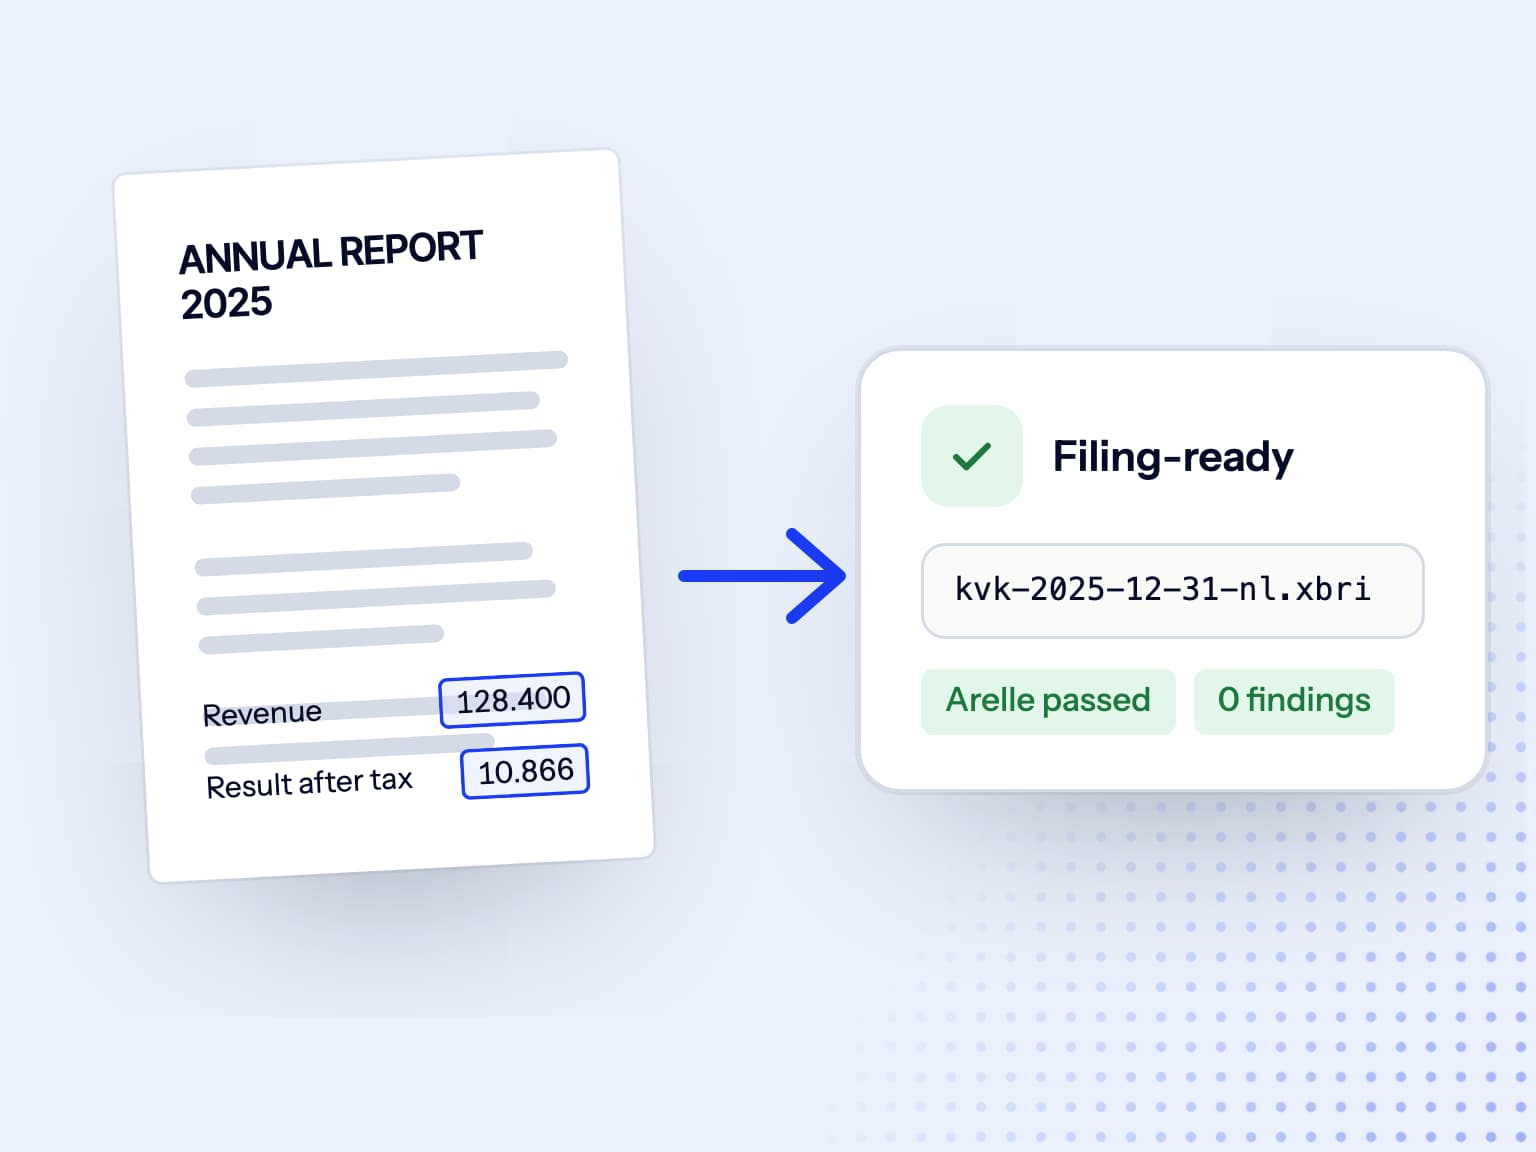
A printed annual report is a love letter from a CFO to a human reader. A regulator, a credit-rating engine, and a peer-comparison dashboard would prefer a spreadsheet, ideally one they did not have to retype. Structured reporting is the compromise: one document, two audiences, no double work. This chapter explains why your filing has to satisfy both at once, who actually demands it, and what happens when the file is technically pretty but semantically nonsense.
Sections in this chapter
Start readingDefinitions from this chapter
- Structured reporting
- Reporting regime where filed information is machine-readable as well as human-readable.
- iXBRL
- Inline XBRL: XBRL facts embedded in an XHTML host document so a single file serves both audiences.
- Fact
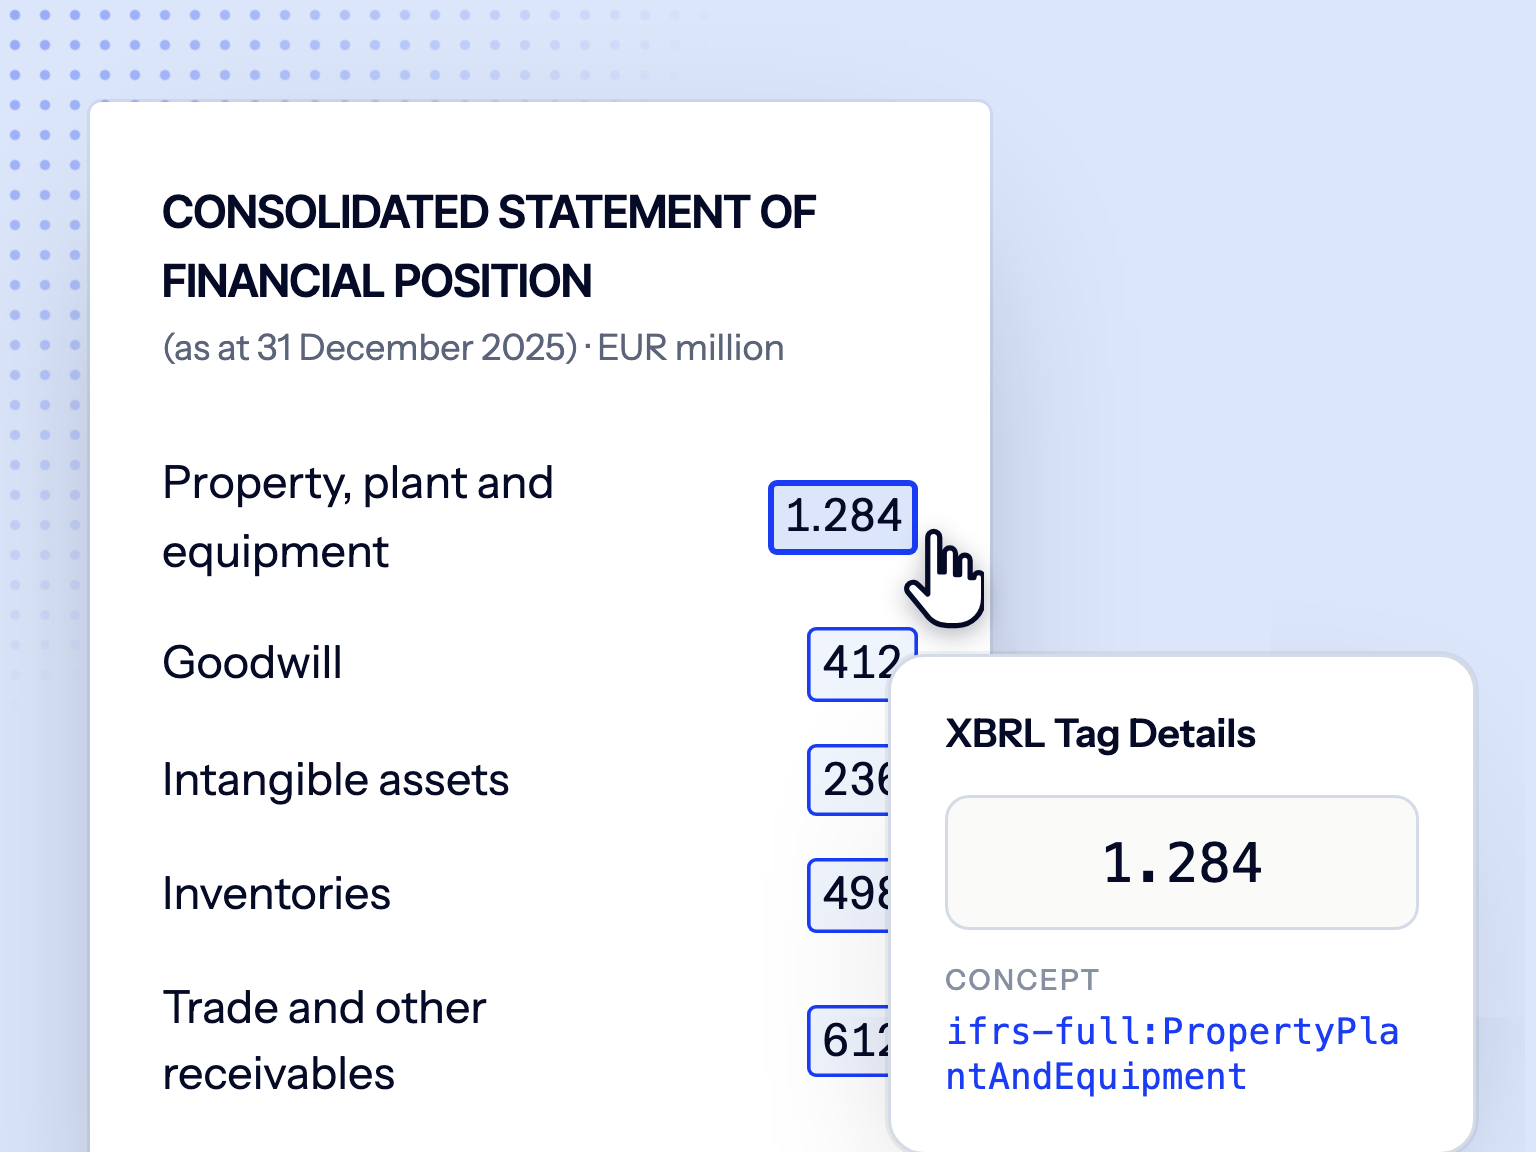
- Concept plus value plus context plus (for numerics) unit and declared accuracy.
- ESEF
- EU mandate for iXBRL IFRS consolidated AFRs of listed issuers.
- EDGAR / EFM
- U.S. SEC iXBRL filing system and rule book.
- SBR
- Dutch Standard Business Reporting framework.
- DPM
- Data Point Model used by EBA and EIOPA for supervisory returns.
- Comparability
- Ability to align facts across filers and periods without rekeying.
Chapter check
3 questions, answered in the signed-in Academy.
These 3 questions count towards your Academy progress
Answer them in the signed-in Academy, where your answers are checked and recorded towards completing the chapter.